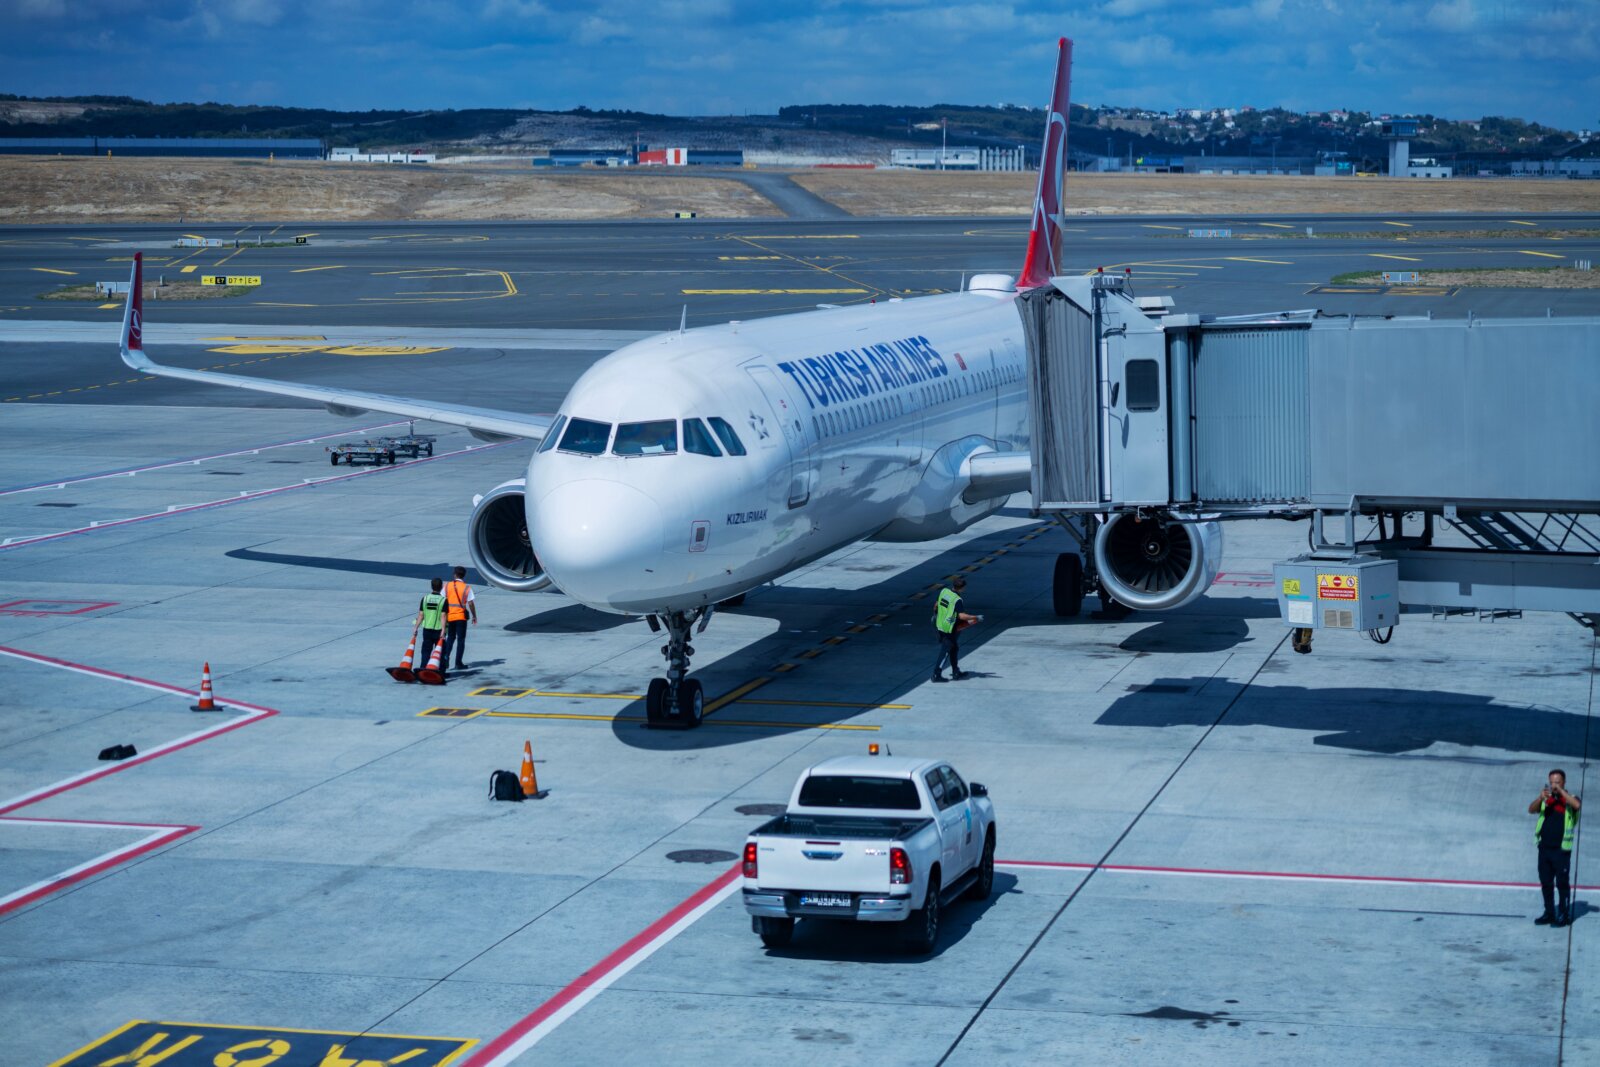
Photo by Frederick Adegoke Snr. on Pexels. Airplane at an airport gate.
A signed order puts work into an aircraft maker’s future. A delivered aircraft records work that has reached a customer. Cash adds another timetable. The latest announcements from Airbus (Euronext Paris: AIR) make those stages worth separating before treating demand as evidence of financial completion.
On 9 October, Airbus announced Avolon’s firm order for 110 aircraft: 35 A330-900s and 75 A320neo Family aircraft. That is a commitment to future equipment, rather than 110 completed handovers. The announcement does not disclose the contract price or payment schedule.
The finance question is sequential: what has been ordered, what has moved through production, and what cash has the process absorbed or released? Each stage needs its own evidence. Adding them together in a single optimistic headline would lose the distinctions that make an industrial business understandable.
Fact: September records delivery, not the October order
Airbus’s September orders-and-deliveries update records 72 deliveries to 37 customers, taking the year-to-date total to 547 aircraft. It also records 17 gross orders for September. Those are separate flows during the month; neither is a euro revenue figure.
The Avolon announcement is dated October. It should not be inserted into September’s reported order total. That would combine events from different reporting periods and make a monthly comparison misleading before any economics were considered.
A delivery count is useful because it identifies completed physical output under the manufacturer’s reporting convention. It cannot, by itself, explain the profitability of that output. A small aircraft and a large aircraft count as one each; the units do not carry a common selling price or production cost.
The same caution applies to comparing orders with deliveries. More orders than deliveries can indicate an expanding workload, while more deliveries than orders can indicate conversion of earlier commitments. Neither relationship alone establishes whether margins improved or cash arrived sooner. The question is what happened to the work already in the system.
Fact: the financial snapshot has an earlier date
In its 29 July half-year results, Airbus reported consolidated free cash flow before customer financing of minus €1,166 million for the six months ended 30 June. Management attributed the outflow mainly to working-capital changes, notably planned inventory build-up supporting the ramp-up across businesses.
That measure is an alternative performance measure adjusted for aircraft-financing cash flows. It is not a statement that customers paid nothing. Nor does the June cash result establish the cash outcome of September deliveries.
The results also set a 2026 target of around 870 commercial aircraft deliveries, conditional on assumptions about disruption. Comparing that dated target with September’s 547 leaves 323 aircraft, or roughly 108 a month over October–December. This is arithmetic against July guidance, not a fresh management forecast or proof the target will be met.
Interpretation: a production target needs a calendar
The implied remaining pace is useful as a question for subsequent reporting. It identifies how much delivery work would remain under that target. It does not identify which aircraft are ready, which components are missing, or how many handovers customers can accept in a particular week.
Multiplying September’s deliveries by twelve would offer an annualised number, but it would assume an even pattern that this calculation has not demonstrated. Likewise, treating the remaining three months as identical would impose a convenient calendar on a production process. Neither shortcut supplies evidence of the actual schedule.
Installed capacity, operating output and customer delivery are different observations. A building or production line can exist before it produces at its intended pace. Equipment must be available, work must progress and completed units must reach the point at which a handover is recorded. Those are general process distinctions, not claims that a particular Airbus facility has failed.
For an assessment of the remaining year, the useful evidence would connect those stages: disclosed output, delivery progress and explanations of timing changes. A delay deserves a cause and a scale. Moving a handover between months is different from losing an order; an aggregate monthly count cannot tell us which occurred.
Interpretation: trace funding alongside the aircraft
Working capital describes resources tied up in the ordinary operating cycle, including inventory and amounts owed between a business and its customers or suppliers. Cash timing becomes clearer when those balances are followed alongside output. A busier factory can require more funding before it releases finished work.
Consider a deliberately simplified hypothetical manufacturer. It spends €6 million on components and labour before receiving an €8 million final payment. If payment follows in a later period, the first period contains the outlay and the second contains the receipt. The sequence can create an interim funding need even when the completed sale produces a positive difference between these two amounts.
Introduce a €3 million customer advance before production and that interim need changes. The total assumed final sale value stays €8 million, with €5 million still to collect. The advance changes when funding is available; it does not create an additional €3 million of sales. These are invented inputs, not Airbus contract terms or a margin model.
This example is intentionally incomplete: overheads, tax, financing and other costs are omitted. Its purpose is to show why delivery volume and cash flow cannot be substituted for each other. Without contract-level payment terms, allocating a precise cash receipt to each aircraft would manufacture certainty from an output count.
Management’s inventory explanation therefore gives the June outflow context, while leaving a further test. Inventory assembled for later deliveries should be assessed against subsequent conversion and cash reporting. Calling an outflow “planned” describes management’s intention; it does not establish the eventual return from the spending.
Who could benefit?
Fact: Airbus (Euronext Paris: AIR) is the manufacturer receiving the order. Its half-year results connect higher commercial-aircraft revenue with higher deliveries and services. Interpretation: converting more aircraft into accepted handovers could support revenue and release inventory funding over coming quarters. That benefit depends on production costs, customer payments and delivery mix; the October order supplies no basis for assigning a contract margin or a cash date.
Fact: Safran (Euronext Paris: SAF) and GE Aerospace (NYSE: GE) have a programme-level connection through CFM International, their 50–50 engine joint venture whose LEAP family powers A320neo aircraft. This is wider supplier exposure, not evidence that Avolon selected LEAP engines for this order. Interpretation: where customers choose LEAP and engines are delivered, additional A320neo production can support equipment sales; aircraft subsequently entering service can enlarge the fleet requiring maintenance over years. The sequence matters: an aircraft order is neither an engine selection nor a completed service sale. Neither supplier’s group earnings contribution from these 110 aircraft is established here.
Who’s at risk?
Interpretation: Airbus bears the reverse cash-timing risk. If components or customer acceptance delay handovers while production spending continues, inventory can retain funding for longer. Its June inventory explanation makes this a relevant operating mechanism, without proving that a new delay has occurred. Over the remaining quarter and subsequent reporting periods, delivery progress alongside inventory and cash movement would distinguish conversion from prolonged funding needs.
Fact: Safran’s July results identify supply-chain production capabilities as a watch item. GE Aerospace’s July results report higher commercial-engine equipment revenue alongside a contraction in that segment’s margin, attributed to installed-engine growth, investment and inflation. Interpretation: Safran and GE therefore need profitable output and adequate service capacity, rather than volume alone. Faster production can require spending before later maintenance receipts; delays can defer equipment sales. These are material questions for their engine businesses, but the sources do not quantify an Avolon-specific effect, and both groups serve other aircraft programmes. Engine deliveries, service activity, margins and cash reporting over quarters and years would change the assessment; higher activity alone does not establish higher returns.
Speculation: two paths remain possible
One conditional scenario is that work already funded moves into completed deliveries and receipts, improving cash generation in a later period. Another is that output or customer acceptance takes longer, leaving resources tied up for longer. No probability is assigned to either path here, and neither is presented as a prediction.
The limitations are substantial. The monthly update provides counts; the half-year release provides an earlier consolidated financial picture; the new order announcement supplies no payment schedule. These sources cannot establish the cash contribution of the Avolon contract or a definitive fourth-quarter delivery outcome.
The next assessment should change when new evidence closes those gaps: dated deliveries, updated management guidance and financial statements explaining inventory and cash movement. A large order is commercially relevant. Following its conversion gives that relevance a measurable financial shape.
Sources checked on 12 October 2026. This is informational analysis, not personalised investment advice.